
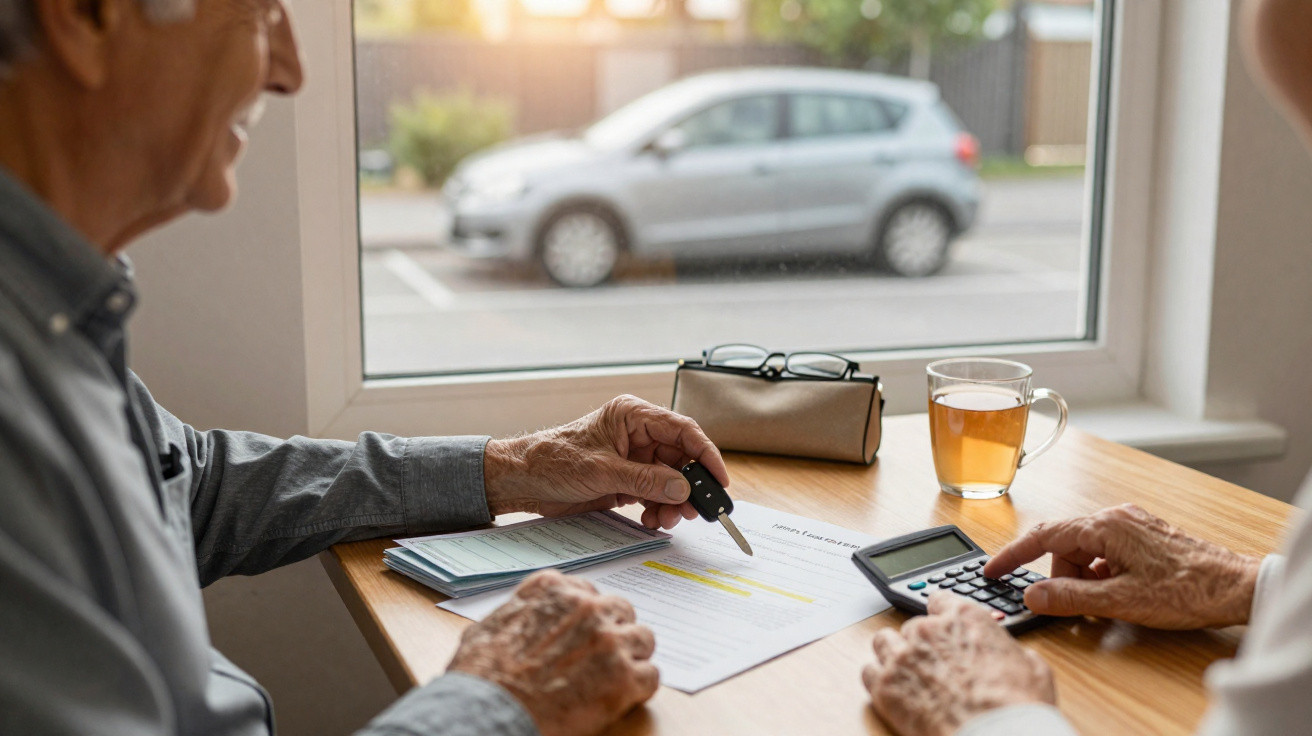
At 94, this man now lives in a care home. His days are structured around meals, visits from relatives and a few walks in the home’s garden. His car, meanwhile, is parked elsewhere and has not been used for months. Yet the direct debit still goes out: almost €700 every month for a vehicle he no longer drives and which the dealership now refuses to take back. His family’s confusion grows with every bank statement. How can someone keep paying for a car when they are no longer physically able to get behind the wheel? We all know the point at which a contract signed years earlier becomes far more burdensome than expected. Here, the story takes on a particularly cruel dimension. At that age, every euro matters.
A car that is no longer useful, but a contract that remains fully active
This 94-year-old’s circumstances mirror those of many families facing a sudden move into a care home. Just a few weeks can transform an entire daily life: a home is left behind, routines vanish and costs begin to mount. The car, once a symbol of the freedom to buy bread or visit a neighbour, abruptly becomes a cumbersome possession. It is no longer driven, but it still costs money. In his case, the €700 monthly payment is a serious burden alongside the already high cost of accommodation in specialist care.
At that rate, the bill comes to €8,400 over a year, before insurance, potential maintenance, parking or charges linked to a late return of the vehicle are included. The family approached the dealership with a straightforward request: take the car back so the monthly payments can stop. It refused. The vehicle may be too new, the agreement may be too restrictive, or its trade-in value may be too low compared with the outstanding amount. Behind this highly administrative language lies one clear fact: a 94-year-old man is funding a car he can no longer use.
The heart of the issue is often the type of finance agreement originally signed. A lease with an option to buy, a long-term lease or a standard loan do not provide the same rights or exit routes. A dealership is not automatically required to take back a car, even if the customer can no longer drive. Let us be honest: hardly anyone reads every line of an agreement when buying a car. Several years later, however, those small clauses can determine the cost of thousands of euros.
Steps to take before panic sets in
The first step is to find the exact agreement and establish which finance arrangement applies. Check the agreed term, the amount of remaining instalments, early termination penalties and the conditions for returning the vehicle. A copy of the order form, lease agreement and repayment schedule will already make the situation clearer. If the older person can no longer manage their affairs alone, an authorised relative or legal guardian can request these documents. A written request always provides a useful record.
A common mistake is accepting the first answer given over the telephone too quickly. A “there is nothing we can do” response often needs to be set out clearly in writing. Ask whether early return is possible, whether the agreement can be transferred, or whether the car can be sold to settle the finance. Some companies also offer to buy out the agreement. This is rarely free, but it can sometimes cost less than continuing payments for many more months. The aim is not to look for a miracle; it is to compare very real losses.
In cases like this, support from a consumer organisation, an ombudsman or a legal adviser can alter the balance of power. The family should not have to face technical letters alone, particularly when the instalments are already eating into the care home budget.
“An oral refusal is not a final answer: ask for the reasons, figures and exact conditions in writing.”
- Request the outstanding capital or lease payments owed on the precise date.
- Obtain valuations of the car’s true value from several professionals.
- Check whether there is insurance for loss of independence or incapacity.
- Contact the complaints department before considering referral to an ombudsman.
- Keep every letter, email and direct-debit statement.
When moving into a care home exposes overlooked contracts
This case extends far beyond a car costing €700 a month. A move into a care home often forces families to list everything that continues to be debited: subscriptions, insurance policies, loans, mobile plans, home services and sometimes even a second property. In the first few days, the priority is human. Relatives must organise visits, understand the care arrangements, clear a flat and reassure a parent who is losing their bearings. Contracts, however, rarely wait with any sensitivity. They simply continue according to their cold timetable.
The situation of this 94-year-old man also raises a simple question: how far does a professional’s responsibility extend when a customer has clearly become vulnerable? A dealership does not always have a legal duty to take back a vehicle. Yet it may have commercial discretion, a resale network or a negotiated trade-in solution. Between strict legal rights and common sense lies a space that some businesses choose to make available. Others do not. For relatives, that difference may represent several months of disposable income.
Planning ahead does not mean constantly imagining the worst. It can be as simple as keeping a folder in a drawer containing agreements, insurance details and the contact information for organisations to call. Many older people keep a car “just in case”, even as journeys become infrequent and the vehicle loses value. The discussion is delicate and can sometimes be painful. Yet talking early enough about driving, independence and expenditure prevents the decision from one day arriving with the force of a slamming door.
One monthly payment too many can upset a family’s balance
At €700 per month, an unused car is no longer merely a poor financial decision: it becomes a daily source of anxiety. For a care home resident, that amount could pay for personal support, unreimbursed treatment, suitable clothing or easier visits for relatives. This 94-year-old man’s family is not asking for special treatment. It is seeking a reasonable way out of an agreement that no longer makes sense in real life. Many people immediately recognise that disconnect.
The power of this story may lie in how ordinary it appears. A signature, a vehicle, a direct debit: nothing seems remarkable at first. Then dependency arrives, priorities shift, and documents once put away without a second thought become decisive. Relatives then discover that a car can cost almost as much as a small room while providing no service at all. It also raises questions about how long-term finance is sold to customers whose circumstances can change abruptly.
There is still room for discussion, negotiation and, at times, commercial goodwill. Families going through this period would benefit from sharing the steps they have taken, the refusals they have received and the solutions they have secured. Behind every difficult-to-end agreement, there is rarely carelessness. More often, a life has changed faster than the paperwork.
| Key point | Detail | Benefit for the reader |
|---|---|---|
| Identify the agreement | Lease with an option to buy, long-term lease or standard loan: the available exit routes vary. | Avoid negotiating without knowing your rights. |
| Obtain a written response | The dealership or finance provider must set out the options and costs. | Compare solutions using real figures. |
| Use available routes of redress | Complaints department, ombudsman, consumer organisation. | Avoid facing a refusal in isolation. |
Frequently asked questions
- Is a dealership required to take back a financed car? No, unless the agreement provides for this. A trade-in may be offered commercially, but it is not automatic.
- Can a lease with an option to buy be ended because someone moves into a care home? The agreement does not end automatically. Early return, transfer or buying out the remaining payments must be considered.
- Can the family sell the vehicle? It depends on the finance arrangement. Under a lease with an option to buy, the finance company often remains the owner until the final purchase.
- Who should be contacted if the professional refuses? Start with the complaints department, then refer the case to the relevant ombudsman or a consumer organisation.
- Should insurance be kept for a car that is no longer driven? Yes. At the very least, third-party liability cover is generally still required until the vehicle is sold, transferred or scrapped.
Comments
No comments yet. Be the first to comment!
Leave a Comment