
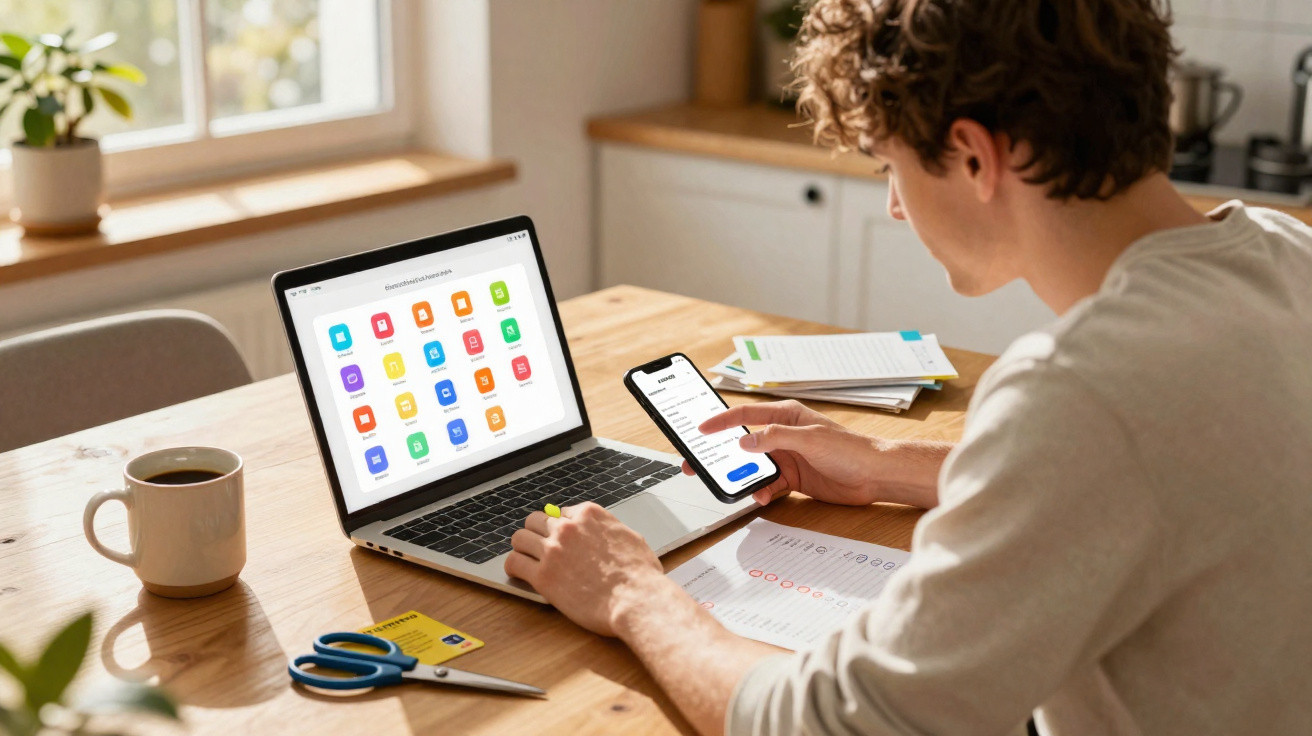
The alerts arrive before anything else.
A gentle ping on your phone or an unobtrusive email lands in your inbox: “Your payment has been processed.” You cannot recall purchasing anything today. Then it dawns on you that these are simply your regular subscriptions, passing unnoticed in the background: the music app, the meal box and the fitness platform you have not opened for two weeks. Nothing seems alarming; they are only small, supposedly “normal” amounts.
You had assured yourself that they were optional, adaptable and simple to cancel. Still, they leave your account punctually, just like rent and electricity.
At some point, “just to try” became “it just renews.”
You never consciously made that choice.
You simply stopped noticing.
The quiet habit that freezes your budget
The crucial change does not occur when you take out a subscription.
It begins in month two, when you do not pause to question it. You allow the payment to clear because “it’s only $7”, “it’s already set up” or “I’ll look at it later.” That silent inaction is what converts optional spending into a fixed expense.
Your bank does not raise the alarm.
Your budgeting spreadsheet does not sound a siren either. These modest automatic payments fade into the scenery, appearing every bit as legitimate as your health insurance.
Consider Emma, 32, who promised herself she would be “careful with subscriptions”. During a demanding week at work, she joined a meditation app. “Just for one month,” she told herself. A meal-kit trial followed, along with extra cloud storage and a premium note-taking tool. None of it registered as proper spending.
Three months on, she eventually checked her banking app.
There were fourteen recurring charges: some for apps she had not used in weeks, and one she genuinely could not recall at all. Separately, they ranged from $2.99 to $19.99. Combined, they came to almost half of her grocery budget. They could have continued quietly for years.
The process is straightforward: repetition reshapes your thinking.
A one-off cost can feel open to negotiation, even slightly playful. By the second or third payment, your mind begins placing it in the “normal life” folder. Come month six, your brain hardly registers it. It has become part of the framework of your month, much like commuting or paying rent.
This is how voluntary costs gradually become pseudo-obligations. It is not necessarily because you urgently require them, but because you have repeated the payment so often that challenging it now seems like hard work.
How to unfreeze expenses without living like a monk
One small, deliberate action can alter the whole picture: make every recurring cost reapply for its role each month.
This does not require an enormous spreadsheet or a four-hour budgeting bootcamp. Instead, whenever a charge appears, ask one question: “If this didn’t exist yet, would I sign up for it today at this price?”
That brief mental reset interrupts the force of routine.
It returns the cost to the realm of intentional decisions, where your answer can be yes, not now or no thanks. You’re not cancelling joy, you’re cancelling autopilot.
Many people immediately choose the extreme route. They attempt a “no-spend year”, remove every app or cancel every subscription in one unforgiving Sunday. For roughly a week, it feels heroic. Then everyday life intervenes, the gap becomes uncomfortable, and old patterns reappear under different labels.
A gentler approach is usually more workable.
Choose one day each month to review the previous 30 days of transactions. It need not take five hours; give it fifteen minutes. You are not there to criticise yourself, only to ask, “Does this still match the life I want right now?” Honestly, hardly anyone manages this every day. Once per month, however, is probably achievable.
Sometimes the bravest financial decision is not to earn more, but to admit: “I don’t actually value this enough to keep paying for it.”
- Step 1: List your recurring payments
Open your banking app and note down every repeating charge: apps, boxes, memberships, software, “small” donations and warranties. - Give each payment a ruthlessly honest label
Apply three straightforward tags: “Love”, “Use but neutral” and “Forgot / Meh”. That final group is where your budget can uncover real value. - Decide one action per line
Keep it unchanged, downgrade it, pause it or cancel it. Even selecting “keep” matters, because it turns an idle habit into an explicit yes. - Set an expiry date
For anything you retain without loving, create a reminder for 60 days later. If you still do not care about it then, remove it.
Living with flexible expenses in a world that wants everything on autopay
We live in an economy that favours subscriptions over one-off purchases.
Every provider wants to slip into the “fixed cost” part of your life: coffee passes, car “memberships”, toothbrush refills and wardrobe boxes. It may appear modern and seamless on paper. In reality, it reduces your ability to decide each month what genuinely matters.
The meaningful change is not about rejecting subscriptions altogether. It is about declining to give something permanent default status simply because its payment is automated.
| Key point | Detail | Value for the reader |
|---|---|---|
| Notice quiet “fixed” habits | Identify small repeating charges that no longer feel like choices | Rebuild awareness of where your money really goes |
| Reassess your expenses | Ask whether you would subscribe again today for the same price | Remove dead-weight costs without severe deprivation |
| Preserve flexibility | Use monthly reviews and expiry dates for services | Safeguard your freedom to adjust your lifestyle as your needs evolve |
FAQ:
- Question 1 How can I tell whether an expense is genuinely “optional”, rather than whether I am simply being too hard on myself?
Focus on consequences rather than guilt. If cancelling it would cause only minor inconvenience or a little administration, it is optional. If it puts your health, safety, work or relationships at risk, it is closer to fixed.- Question 2 Is it wrong to retain subscriptions that I do not use constantly?
No. The aim is intention, not perfection. If you deliberately decide, “I like having this on standby even if I don’t use it daily,” that is a legitimate choice rather than a financial leak.- Question 3 How frequently should I check my recurring expenses?
Monthly is a useful routine. If that seems too demanding, begin every quarter. Consistency matters more than intensity.- Question 4 What should I do about annual subscriptions that seem cheaper overall?
They may be useful, but they can also disappear from your monthly awareness. Set a calendar reminder a few weeks before renewal and ask again: “Would I buy this today?”- Question 5 How can I avoid “just $5” offers that build up over time?
Set yourself one simple rule: wait 24 hours before adding any new recurring charge, then decide what you would cut to pay for it. If nothing seems worth removing, the new expense is probably not worth it either.
Comments
No comments yet. Be the first to comment!
Leave a Comment