
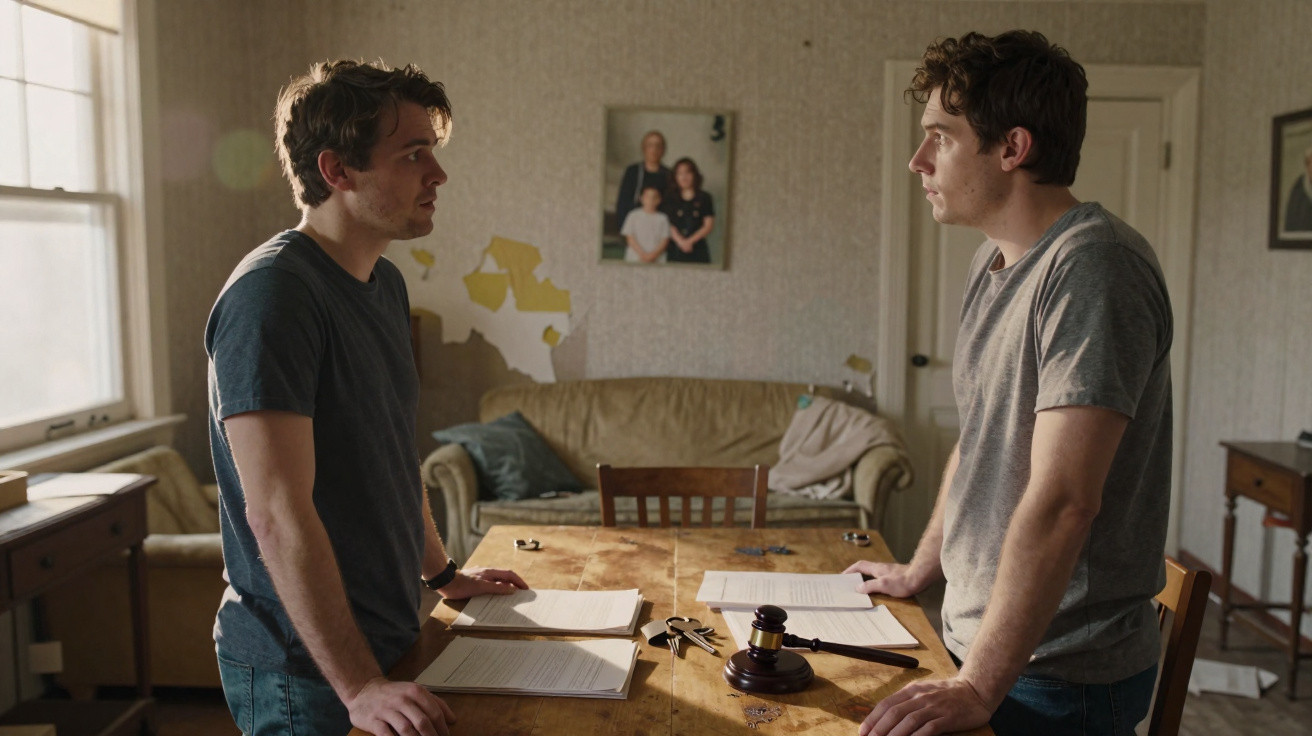
The peeling wallpaper was the first thing they learnt to overlook. After that came the scent of damp, creeping up the stairs week by week, a muted alarm nobody wanted to acknowledge. Their father’s old family home was meant to be his gift: the final piece of him that all three siblings could share. Instead, it turned into a battleground, visited only for photographs, recorded-delivery letters and conversations conducted through solicitors.
One sibling wanted a sale, another wanted everything kept “as it was”, while the third remained caught between them, watching the property deteriorate and the unpaid bills mount.
On the gate, a weathered “For sale” board fluttered in the breeze.
The real tempest, however, was unfolding in the family WhatsApp group.
When a dream inheritance becomes unpaid work
An inheritance can sound like a blessing when it appears merely as a sentence in a notary’s letter: a house, some land, perhaps a little money. On paper, it seems like an unexpected bonus that life never promised. Then the calls from the tax office begin, insurance reminders arrive, and the notary sends an uneasy email requesting “a clear position from all heirs”.
What initially looked like a gift can quickly resemble a part-time job: no pay, no annual leave, only obligations.
Where the heirs are siblings who cannot decide what to do, the house may become stuck in an odd state of limbo. Nobody properly lives there, yet everyone quietly funds its gradual decline.
Consider this familiar situation. Three brothers inherit their parents’ former home in a small town. The youngest lives close by and keeps his tools in the garage. The eldest, who lives overseas, wants a quick sale so that everyone can “move on”. The middle brother holds on to the prospect of renovating it one day, “when things calm down”.
Nobody wants to play the villain. Equally, nobody wants to spend money on major repairs. As the years pass, paint begins to split, the roof develops leaks and damp takes hold.
The bills keep coming regardless: property tax, co-ownership charges, insurance for an empty house and utility costs to prevent pipes from freezing. The house steadily drains each person’s bank account, but the deeper harm lies elsewhere: in resentments that solidify whenever a message receives no reply.
Legally, however, doing nothing carries a price. In many countries, heirs become jointly responsible for inherited property as soon as they accept the inheritance. If nobody takes action, the debts do not vanish; they simply become a shared burden.
Judges regularly encounter such disputes: one sibling pays “to avoid trouble”, another will not contribute a penny “until we agree on the big picture”, and a third disappears altogether. Once the matter reaches court, the judge is not concerned with who cried most at the funeral.
The court examines who used the property, who paid which costs and who obstructed particular decisions. Ultimately, it decides who must pay for the roof that nobody repaired.
From family drama to legal reality: who pays when nobody agrees?
One step can often alter the entire situation: applying to end the joint ownership. This dry legal term describes a very straightforward position. You are telling the court: “We’re stuck. We can’t manage this together. Decide for us.”
That application can result in a forced sale, with the judge overseeing both the sale process and division of the proceeds. It can be emotionally brutal, particularly where the property is the family home, but it ends the gradual drain of unpaid bills and unending arguments.
It also compels everyone to replace vague promises with figures. How much has each sibling paid already? Who occupied the house? Who allowed the garden to turn into a jungle that now costs thousands to clear?
The major trap for many families is waiting “just a little longer”. One sibling moves into the house “for a few months”, pays no rent and never formally resolves the arrangement. Another covers every tax bill for ten years, only to find they must evidence every individual transfer to obtain reimbursement.
Realistically, almost nobody stores every receipt and bank statement in flawless order for a whole decade. Yet these are often precisely the documents judges need when deciding who should carry the financial cost of a decaying house.
What seems “fair” at the family table does not necessarily follow the law’s logic. Where you alone have used the house for years, a court may view you as owing rent to the other heirs. If you rejected every offer to sell, you cannot then claim that the property was a burden you never chose.
In these disputes, judges effectively carry out a moral reckoning using legal instruments. They assess three central factors: benefit, inertia and effort. Who gained from the house? Who prevented solutions? Who actually paid to avert disaster?
A sibling who uses the property without charge, stores belongings there or lives there almost full-time may be regarded as having received a benefit. The person paying tax and emergency repair costs may seek compensation. Someone who says nothing for years and reappears only when the sale is due risks appearing less credible.
The court doesn’t heal old family wounds, it just writes them into a judgment.
That judgment might, for instance, require the sibling who lived there to repay part of the costs, or deduct repair bills from their share of the sale proceeds. Cold figures imposed on intensely personal memories.
How to stop an inheritance becoming a legal life sentence
The first meaningful action will often take place well before a judge is involved: put arrangements between siblings in writing, even if it is only an email. “You live in the house, you pay this. I pay that. We talk again in six months.” It need not be perfect; it simply needs to exist.
If one person uses the property, agree a modest rent or compensation, even if it is symbolic. If someone pays a substantial bill, circulate the invoice and record everyone’s response. These straightforward practical steps create an evidence trail that a judge can later follow.
A brief written agreement prepared with a notary can also set the rules in place: who is responsible for what, who pays what and for how long. It does not take away the pain of bereavement. It can, though, prevent the pain of waking up to a legal claim.
The most frequent error is mistaking loyalty to the past for unquestioning loyalty to bricks, walls and tiles. Keeping the house “because it was Mum’s” can sound romantic, until you are cleaning mould from the bathroom on a Sunday morning while debating a plumber’s estimate on speakerphone.
We have all faced that moment when agreeing feels easier than confronting a dispute. You accept the inheritance without asking serious questions, allow your brother to “handle the paperwork”, and agree when somebody says “we’ll see that later”.
But later arrives, bringing late-payment charges, court papers and the sinking feeling of seeing the family name on an official envelope. Admitting that you cannot maintain a house, or that selling is the sole way to protect those still living, is not a failure. It is simply honest.
Sometimes, the most loving decision you can make for a dead parent is to stop sacrificing the living for a piece of property they no longer need.
- Talk early – Within weeks of the inheritance, arrange one clear discussion involving every heir, preferably with an impartial third party such as a notary or trusted friend.
- Write things down – Even an imperfect email summary of “who pays what” can prove invaluable if the conflict later escalates.
- Set a deadline for decisions – Agree a date by which to decide whether to keep, let or sell. An indefinite “we’ll see” is how properties decay and relationships fracture.
- Record every expense – Keep a simple shared document for tax, repairs and insurance, including who paid and when. Your future self will be grateful.
- Seek help before court – Mediators, notaries and legal clinics are available. The sooner you speak with someone neutral, the more options remain open.
When an inherited house outlives the family that built it
There is something particularly cruel about watching a house collapse into disrepair while family members argue about who loved their parents most. The roof does not care. The garden does not care. The court certainly does not care.
What began as a symbol of togetherness becomes a mirror for every small grievance, childhood rivalry and old remark that still stings. Some siblings stop speaking for years because of a crumbling garage or a dark, unused sitting room. Others manage to sit around the kitchen table one final time, sign the sale documents and go for a coffee afterwards, partly relieved and partly heartbroken.
These situations do not fit neatly into legal categories. A judgment can determine who pays, who owes and who receives what proportion of the sale. It cannot determine who will turn up next Christmas.
Perhaps that is the true question behind the damp walls and unpaid bills: what are you willing to lose to keep a house, and what are you willing to release to keep a brother or sister?
| Key point | Detail | Value for the reader |
|---|---|---|
| Put rules in writing quickly | Set out who uses the property, who covers each cost and for what period | Reduces unexpected problems and provides strong evidence if a dispute reaches court |
| Use legal tools before it is too late | Ask a notary, mediator or judge to end joint ownership or require a sale | Halts the financial drain and avoids a “life sentence” of endless co-ownership |
| Separate emotion from responsibility | Recognise that memories are not the same as bricks and unpaid taxes | Supports calmer decisions and safeguards both your money and relationships |
FAQ:
- Question 1 What happens if I refuse to pay my share of the house expenses as an heir?
- Answer 1 The other heirs may pay on your behalf and then ask a judge to reimburse them from your share of the inheritance, or directly from you. Courts generally regard co-heirs as jointly responsible for essential costs such as taxes and urgent repairs.
- Question 2 Can one sibling force the sale of the inherited house?
- Answer 2 Yes. In many legal systems, nobody can be compelled to remain in joint ownership indefinitely. A sibling may ask the court to end the co-ownership, which frequently results in a judicial sale where no agreement can be reached.
- Question 3 What if one heir lives in the house for free?
- Answer 3 A judge may decide that this heir benefited from the property and order compensation for the others, sometimes by reducing their share of the sale proceeds or treating the benefit as unpaid rent.
- Question 4 Can we avoid court with a simple written agreement between siblings?
- Answer 4 Yes. A private written agreement can govern use of the house and allocation of costs. Having it reviewed or formalised by a notary adds legal weight and may prevent later disputes.
- Question 5 Is it possible to renounce an inheritance that looks too risky?
- Answer 5 In many countries, you may refuse an inheritance or accept it “up to the amount of the assets”, limiting personal exposure where debts exceed the estate’s value. This requires a formal procedure, usually through a notary or court.
Comments
No comments yet. Be the first to comment!
Leave a Comment