
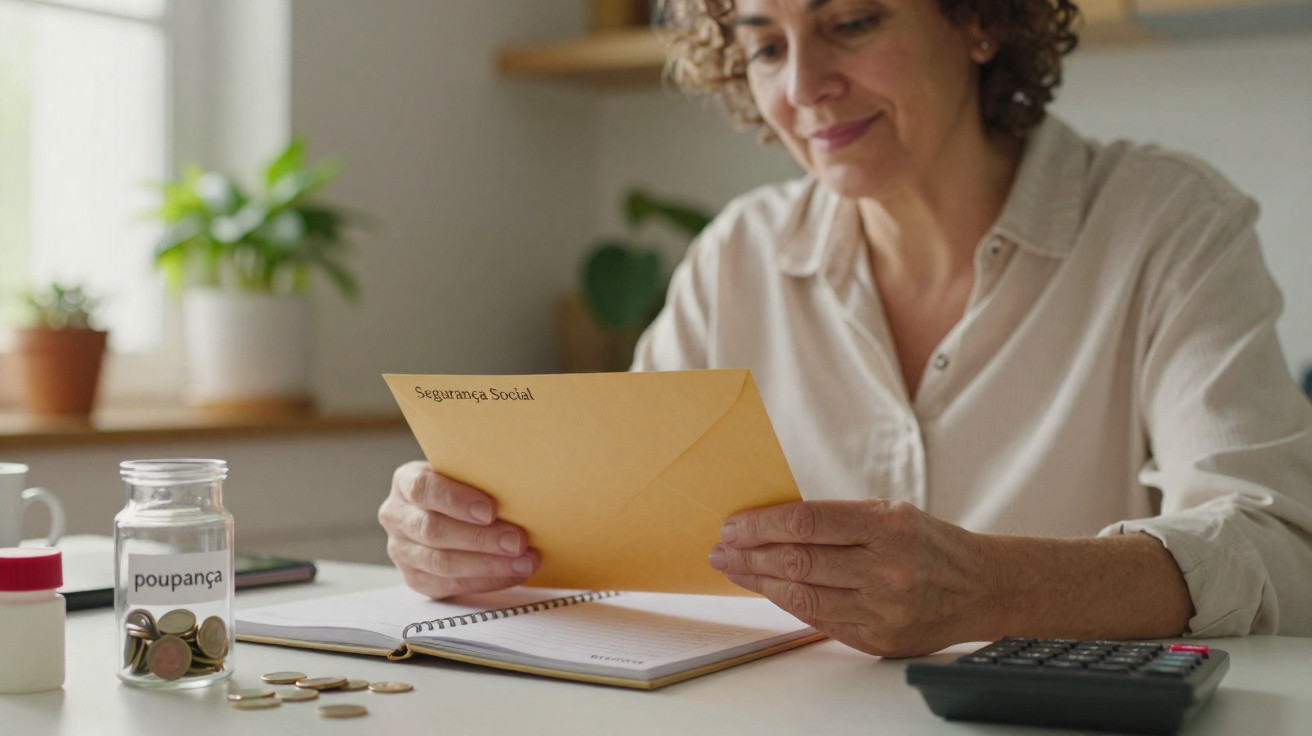
Evelyn, 72, found the letter on her kitchen table, partly covered by a supermarket leaflet. She had already assumed it would bring bad news: one more bill or another reminder that life costs more than it did last year. She opened it with the familiar knot of worry many retirees feel while waiting for Social Security news.
She had seen the Facebook rumours and caught fragments of television reports: “Higher checks in 2026.” It sounded welcome, but almost too good to believe – like so many headlines that never seem to affect your own postbox.
When she spotted the newly projected figure for her monthly benefit, she had to sit down. It was not a windfall, but it could mean renewing a prescription without giving up a bag of shopping. The amount was modest, yet it felt unexpectedly significant.
Across the United States, millions of people may soon experience that same reaction when they open their own letter or log in to their SSA online account.
What the 2026 Social Security update really changes for your monthly check
Put simply, the 2026 Social Security update confirms what retirees have been waiting to hear: monthly payments are set to rise. It is not a life-changing jackpot or a miraculous pay rise, but it is a genuine increase that will appear in the monthly deposit.
The change comes from the mechanism that shapes benefits each year: the cost-of-living adjustment, known as COLA. It follows changes in prices and lifts payments so that benefits do not fall entirely behind the cost of everyday life.
The 2026 update suggests that this year’s adjustment will be more than merely symbolic. It is intended to recognise the persistent costs of housing, food, medical treatment and utilities, none of which have exactly returned to “normal”. The message from Social Security to retirees and other beneficiaries is clear: the pressure on household budgets is being acknowledged.
The key question is no longer only, “How much more will I get?” It is also, “What difference can that increase make to my day-to-day life?”
To understand the possible effect, imagine three people looking at the same 2026 update. Maria, 67, lives by herself in a small flat and receives roughly $1,700 each month. A moderate COLA could add around $40–$60 to her payment. That may seem minor on paper, but it feels different at the pharmacy counter or filling up the car.
Then there is James, 74, a widower who depends largely on Social Security survivor benefits alongside a small pension. His overall income is limited. For him, an increase could mean avoiding the need to put another medical co-payment on a credit card.
Now consider a disabled worker in their 50s receiving SSDI. Their payment is not a retirement benefit in the conventional sense, but they face the same rising prices. The 2026 update applies to them as well. These are the people often overlooked when social media talks about “higher checks”.
Beyond the major national averages and headline figures lies something more vulnerable and more tangible: a little less end-of-month anxiety and a few fewer painful compromises.
The reasoning behind the higher 2026 payments is simple, even if the calculation itself can seem impersonal. Social Security uses inflation data, specifically the CPI-W index, to establish the annual COLA. When prices remain high or continue to rise, benefits for the following year move upwards too – not exactly in step, but in the same direction.
For retirees and beneficiaries, the 2026 update responds to several years of elevated prices that did not truly come back down, even as television charts showed inflation “slowing”.
That is why many experts argue that recent COLAs have not felt like pay rises. They function more like a seatbelt, stopping people from slipping backwards too quickly. If your rent, insulin or car insurance has risen sharply over recent years, the calculation is familiar: a few extra Social Security dollars do not simply undo those increases.
Even so, confirmation of higher monthly payments in 2026 carries an important message. The programme is still adjusting rather than remaining fixed in an era when milk cost $1.50 and receiving a doctor’s bill did not require a deep breath first.
How to use your 2026 Social Security boost so it really changes your month
When your monthly payment rises, one practical step can make the greatest difference: regard the 2026 increase as “new money” and assign it a purpose before it reaches your account. Rather than relying on general intentions, make a straightforward written decision.
For instance, you could decide that half of every increase will go towards essentials such as medication, groceries or utilities. The other half could be directed to a modest emergency fund or towards clearing one particular debt sooner.
In practice, imagine your benefit increases by $55 a month in 2026. You might set aside $30 for a regular expense that has been difficult to manage, perhaps a prescription you have been making last longer or missing altogether. The other $25 could go into separate savings or be used to reduce an ongoing credit-card balance.
There is no financial trick involved. It simply means not allowing the increase to disappear into the general haze of higher prices. Even a few dollars placed in a dedicated “car repair” envelope or a small online savings account can make the next puncture feel less like an emergency.
Of course, we know what commonly happens. The cheque rises, the food bill rises too, and the two changes seem to cancel each other out. Let’s be honest: nobody really does this every day. Yet that is precisely why even a modest plan can be transformative.
Write down, either on paper or on your phone, what the first three months of your higher 2026 benefit will pay for differently. Not permanently. Only three months. Keeping the period short and realistic makes it easier to stick with the plan once everyday life becomes hectic.
There is another aspect of the 2026 update that rarely attracts headlines: the emotional relationship people have with money in retirement. In a difficult month, higher checks affect more than the figures; they can reduce stress. In a better month, that extra amount may finally pay for something that feels like living rather than simply getting by.
Most people know the experience of standing at the till, silently calculating what needs to go back on the shelf. The 2026 increase will not remove that moment for ever, but with deliberate planning it may make it happen less often.
One retired teacher from Ohio put it like this:
“When my Social Security went up last time, I promised myself that $20 of it would be just for joy - a lunch with a friend, a plant for my window. For the first time in years, I didn’t feel like I had to apologize to my own wallet.”
To maintain that mindset while remaining practical, use this simple checklist:
- Check your updated 2026 benefit estimate in your mySocialSecurity account as soon as it becomes available.
- Identify three expenses that caused you the most stress in 2024–2025; these should be the main priorities for the increase.
- Choose one small, guilt-free “quality of life” treat that the additional money will support.
- Discuss your plan with someone you trust – a family member, friend or counsellor – so it is not only kept in your head.
What this 2026 change means for the future of retirees and beneficiaries
The 2026 Social Security update concerns more than the next payment; it also affects how people imagine the remainder of their retirement. For many, the message is mixed. Higher monthly payments offer genuine relief, yet continual discussion of “Social Security’s long-term solvency” creates a persistent underlying concern.
Both feelings can exist at once: appreciation for the increase and an uneasy question about how long the system can continue to meet demand.
This is why the update is worth discussing with family, rather than only considering it in terms of your bank balance. Adult children often do not realise how tightly their parents are managing each month. A confirmed 2026 increase can prompt more open conversations: what happens if rent rises again? Who can help if a large medical bill arrives at the worst possible time?
Speaking frankly about this changes everything. Retirement finances are seldom only about numbers; they also concern dignity, independence and the strong wish not to become a burden to anyone else.
The 2026 boost also brings broader questions into focus. Should people approaching retirement reconsider when they claim benefits? Should disabled workers and survivors anticipate more frequent adjustments while inflation remains unpredictable? These are not abstract policy discussions when you are looking at your own statement.
For some people, the updated payments could make it possible to work part-time slightly less. For others, they may support delaying a claim for a few additional months because the system is plainly continuing to adjust upwards with inflation.
What is evident is that Social Security continues to perform its intended role: moving with economic conditions, even if it can never completely outpace them. The 2026 update confirms that retirees and beneficiaries are not being left stranded at a fixed point while prices accelerate elsewhere.
What remains unresolved, and intensely personal, is how each individual will use that small but genuine current to their advantage rather than allowing it to be lost in the noise of another costly year.
| Key point | Detail | Why it matters to the reader |
|---|---|---|
| Confirmed rise in 2026 payments | The COLA mechanism leads to an increase in monthly benefits for retirees and beneficiaries. | Understand why your cheque will rise and what to expect. |
| Practical effect on the budget | The increases remain modest, but may cover a medical bill, part of the rent or a grocery shop. | See how a few additional dollars can mean less stress each month. |
| Strategy for using the increase | Give the increase a “purpose” – essentials, emergency savings or a small monthly pleasure. | Prevent the increase from being swallowed by inflation and turn it into a genuine source of comfort. |
FAQ:
- How much will Social Security checks actually increase in 2026? Exact figures will be available when the official COLA is announced, using inflation data. Most retirees should expect a percentage increase similar to recent years, rather than a dramatic jump, but one that is noticeable in their monthly deposit.
- Who will benefit from the 2026 Social Security increase? Retired workers, disabled beneficiaries receiving SSDI, and many survivors receiving Social Security benefits will all have their payments adjusted when the COLA takes effect, unless specific offset rules apply to them.
- Will the 2026 increase keep up with rising prices? COLA is designed to track inflation rather than exceed it. It generally helps prevent people from falling too far behind, although many still feel a gap between benefit increases and real-world costs.
- Do I need to apply to get the higher 2026 payment? No. If you already receive Social Security or SSDI, the new amount will appear automatically in your benefit from the first payment after the COLA takes effect.
- Can the 2026 Social Security boost change my tax situation? It can. A higher annual benefit may move more of your Social Security into taxable territory, particularly if you have other income such as a pension or part-time work, so reviewing your tax position in advance is sensible.
Comments
No comments yet. Be the first to comment!
Leave a Comment