
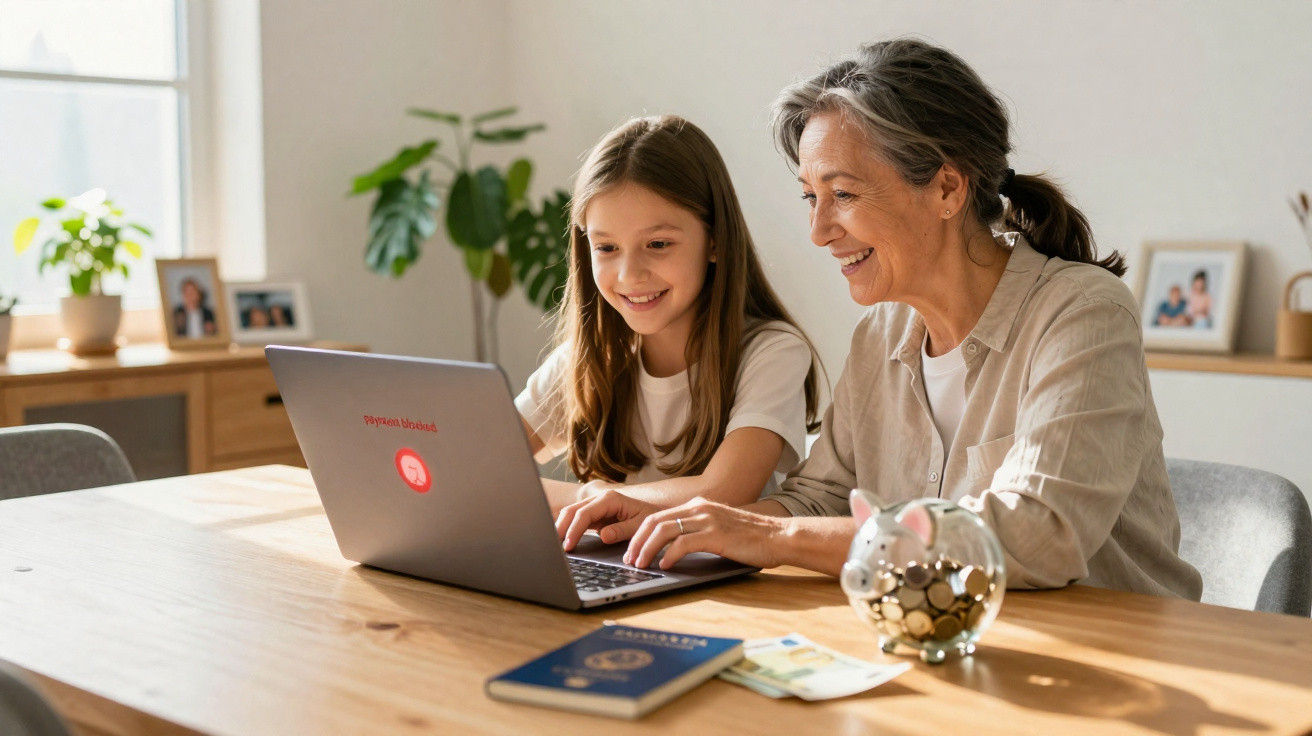
On Sunday after lunch, Martine slips an envelope into her daughter’s bag. Inside are 50 euros for her grandson’s Livret A, just as she has done since he was born. It is a simple, almost automatic gesture, repeated for birthdays, good school results and the festive season. Yet in recent months, some families have discovered at the bank counter or on their banking app that a direct transfer is no longer accepted. A grandparent believes they are giving a welcome gift, the bank stops the transaction, and everyone wonders what has changed. The gift itself is not the issue. It is the route the money takes - and that distinction makes a considerable difference.
Direct transfers from grandparents to a Livret A are now regulated
We all know the urge to get things done quickly: open the banking app, enter bank details, send a small sum and move on. For a child’s Livret A, that approach is no longer always available when the money comes from a grandparent, uncle or godparent. The operating rules for regulated savings accounts have been tightened so that deposits can be identified more clearly. A Livret A is not a current account, even if its bank details may suggest that money can simply be transferred into it without restriction.
In practice, a grandparent can still give 20, 50 or 200 euros to a grandchild. What is restricted is a transfer made directly from their own account to a minor’s Livret A. Take Paul, aged 68, who used to add 30 euros each month to his granddaughter’s savings account. His standing order was rejected by his bank, although the gift itself was never called into question. He must now pass the money to the parents, who can then pay it into the child’s account themselves.
This change follows a rationale of traceability and protection for minors. Banks must know who is funding the savings, where the money originates and who is authorised to act on the account. For a child under 18, that responsibility normally belongs to their legal representatives, often their parents. The generous intention remains unchanged, but the banking route is less spontaneous. Let us be honest: nobody reads the operating terms of a savings account before making a Christmas transfer.
How to keep giving without having the payment blocked
The easiest option is to give the money to the child’s parents, by bank transfer or cheque, while clearly stating that it is intended for their savings. The legal representatives can then make the payment into the Livret A from the account accepted by their bank. Some families would rather hand over an envelope during a meal, after which the parents deposit the sum. It is less immediate than a scheduled transfer, but it avoids rejected payments and calls to customer services on a Monday morning.
Another possibility is to check the exact arrangements with the bank where the Livret A is held. Not every banking interface offers the same options, and the practical rules may be applied slightly differently across banking groups. A common mistake is to assume that the account’s bank details permit every incoming transfer. They are primarily used within the framework approved by the institution. It is also wise to keep a record of the gift, particularly where payments become regular or larger.
Families would do well to separate the emotional gift from the banking transaction. A short note accompanying the payment, proof of the transfer to the parents and an open conversation can prevent many misunderstandings, especially when several relatives contribute to a child’s savings.
“Giving to a grandchild remains entirely possible: you simply need to use the right intermediary when the savings account is held by a minor.”
- A grandparent may make a cash gift to their grandchild.
- Parents or legal representatives can pay into a minor’s Livret A.
- A direct transfer from a grandparent’s account may be refused.
- Written evidence of the gift remains helpful for substantial sums.
A discreet change that makes families rethink their habits
The rule may seem overly fussy when it concerns a few notes for what has become a digital money box. Even so, it is a reminder that a child’s savings are regulated, including when they stem from a warm family tradition. The Livret A remains a popular option: the money is available, the interest is tax-free and its limit is 22,950 euros for an individual. Grandparents can therefore continue to prepare for the future, provided they accept one extra step.
For many people, this minor hurdle raises a broader issue: who really oversees children’s savings? Parents manage the account until the child reaches adulthood, while relatives may wish to contribute without becoming involved in family decisions. Speaking openly about how these sums will be used can ease tensions. Some prefer to fund driving lessons, others higher education or a first home. Money paid in at the age of 8 can take on a very different meaning ten years later.
There is also a tax aspect not to overlook when gifts become particularly generous. Customary presents given at Christmas, for a birthday or to mark academic success are generally accepted if they remain proportionate to the donor’s income and assets. For higher amounts, a manual gift may need to be declared. It is not especially romantic, admittedly, but planning ahead prevents a kind family intention from turning into an administrative headache.
Ultimately, the rule does not shut grandparents out; it asks them to follow a more clearly defined route. A transfer to the parents, a cheque given with a card, an envelope placed beneath the Christmas tree - these habits can sometimes feel reassuring. They also bring a little more conversation about money, a subject families often put off. What if this change were an opportunity to explain to a child why money is being set aside for them, rather than letting a silent transfer do all the work?
| Key point | Detail | Benefit for the reader |
|---|---|---|
| Gifts still allowed | Grandparents can give money to their grandchildren. | The family gesture remains possible without giving up on savings. |
| Direct transfer restricted | A payment from a third party’s account to a minor’s Livret A may be refused. | Helps prevent blocked transactions and unwelcome banking surprises. |
| Best approach | Use the parents or legal representatives to fund the savings account. | Makes it possible to follow the rules while retaining evidence of the gift. |
Comments
No comments yet. Be the first to comment!
Leave a Comment