
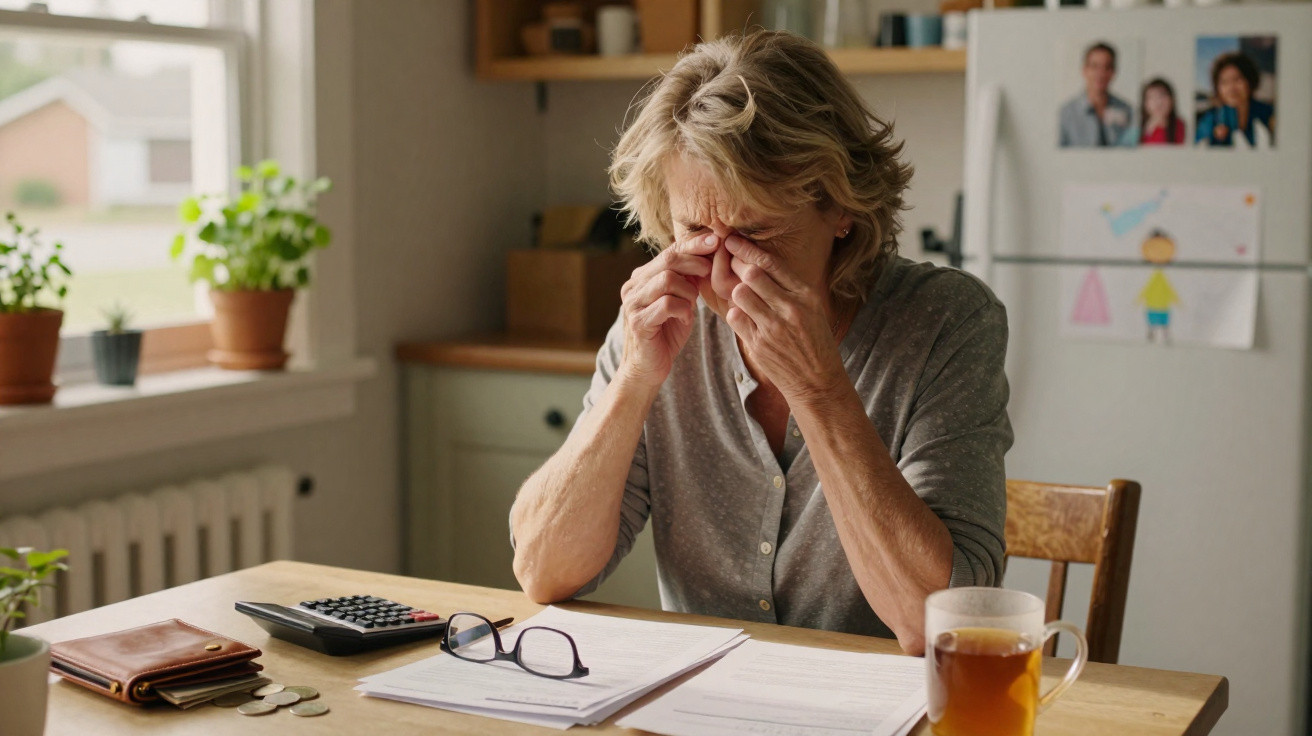
On Tuesday morning, Jane puts her receipt on the kitchen table beside a cup of coffee that has gone cold. At 69, this former administrative worker expected a peaceful retirement, with occasional short breaks, meals with loved ones and a few guilt-free hobbies. On paper, her pension seemed adequate. Yet for several months, every purchase has been scrutinised: vegetables, heating, car insurance and even her grandchildren’s birthday presents. “I am not destitute, but I can no longer breathe,” she says. We all know the feeling of watching our bank balance fall faster than expected. For pensioners, it can become an everyday reality. And it reveals far more than a straightforward budgeting issue.
A retirement that looks adequate on paper, but feels very different in reality
Only a few years ago, Jane believed her pension would be enough to live without anxiety. She had worked for more than forty years, paid off her mortgage and built up a small amount of savings. Naturally, she assumed the hardest years were behind her. Then the bills began rising, one after another, almost unnoticed. Gas, electricity, health insurance top-ups and food shopping: no single cost spirals alone, but the final total becomes burdensome. Retirement changes more than income levels; it also transforms the way every expense is viewed.
Her monthly budget is around £1,750, including her additional pension. After paying for housing, household bills, health cover and direct debits, the amount left may still appear reasonable at first glance. In practice, a £280 boiler repair or a new pair of glasses is enough to throw the month off balance. Jane has put off replacing her old phone, even though its screen is becoming more cracked each week. She is also delaying a dentist appointment. These small postponements reveal just how precarious daily life can become.
The issue is not always that the pension was too low from the outset. More often, it is the gap between income, which rises slowly, and essential costs, which increase without asking permission. Pensioners also face expenses that are often underestimated before leaving work: healthcare, home adaptations, occasional support for a relative or an ageing car. Jane puts it plainly: “Before, I mainly looked at the cost of big purchases. Now, I look at the price of butter.” Let us be honest: nobody chooses to do that every day for enjoyment.
When counting every penny becomes a quiet routine
The first helpful step is to examine spending without judging yourself. Jane began with a notebook kept beside the telephone, before sorting her outgoings into three columns: fixed, necessary and avoidable. This simple exercise helped her spot forgotten direct debits and contracts that had become too expensive. A duplicate insurance policy, an outdated mobile contract and a television service she never used meant she recovered almost £45 a month. It is not dramatic, but over a year it can pay for several food shops or make an energy bill less daunting. Every pound recovered creates a little more breathing room.
Many pensioners wait too long before asking for help, either out of embarrassment or because they assume they do not qualify. Jane herself associated financial support with circumstances far more difficult than her own. Eventually, she arranged an appointment at a local advice centre, where staff checked whether she might be entitled to help with housing, energy or health cover. Not every application succeeds, and the paperwork can feel discouraging. Even so, failing to check is often the costliest mistake. Seeking information is not the same as asking for charity.
A budget should not become a punishment that removes every pleasure. Jane keeps aside a modest amount for seeing friends, buying a book or inviting her grandchildren round for a snack, because a retirement defined solely by worry also takes its toll on wellbeing. As she says with clear-eyed honesty:
“I have learned to be careful, but I refuse to live as though every pleasure were a mistake.”
- Review insurance, energy and mobile contracts once a year;
- Ask a suitable organisation to assess the support that may be available;
- Set aside a small monthly contingency fund, even if it is only £10 or £20, for unexpected costs;
- Compare healthcare costs before giving up necessary treatment.
Fear of the future also affects people who worked all their lives
Jane’s account challenges a persistent belief: that paying into a pension for many years automatically guarantees a comfortable retirement. The reality is more changeable. A pension may appear stable while the cost of living moves forward in quick, small steps. People living alone are often among the first to be exposed, as they must cover housing, insurance and everyday costs by themselves. The feeling of downward mobility cannot be measured in pounds alone: it emerges when someone hesitates to accept an invitation, avoids switching on the heating or delays treatment they genuinely need.
Jane does not see herself as a victim. She values her independence and still manages her home with a discipline she never imagined she would need. But she would like this reality to be heard more widely, without caricature. Between the dream of a comfortable retirement and extreme hardship lies a broad grey area: people who are still coping while calculating every cost. Talking about money with relatives, comparing local options and having entitlements checked can ease a pressure that often remains hidden. Retirement should leave more room for plans than for bills.
| Key point | Detail | Value for the reader |
|---|---|---|
| Essential costs carry significant weight | Energy, health insurance top-ups, housing and healthcare absorb an increasing share of the budget | Better understand why a pension considered adequate may no longer be enough |
| A precise budget can create breathing room | Identify unnecessary subscriptions, contracts and direct debits | Quickly find practical savings without disrupting everyday life |
| Available support is sometimes overlooked | An assessment may uncover entitlements connected with housing, energy or healthcare | Avoid missing out on accessible support |
Comments
No comments yet. Be the first to comment!
Leave a Comment