
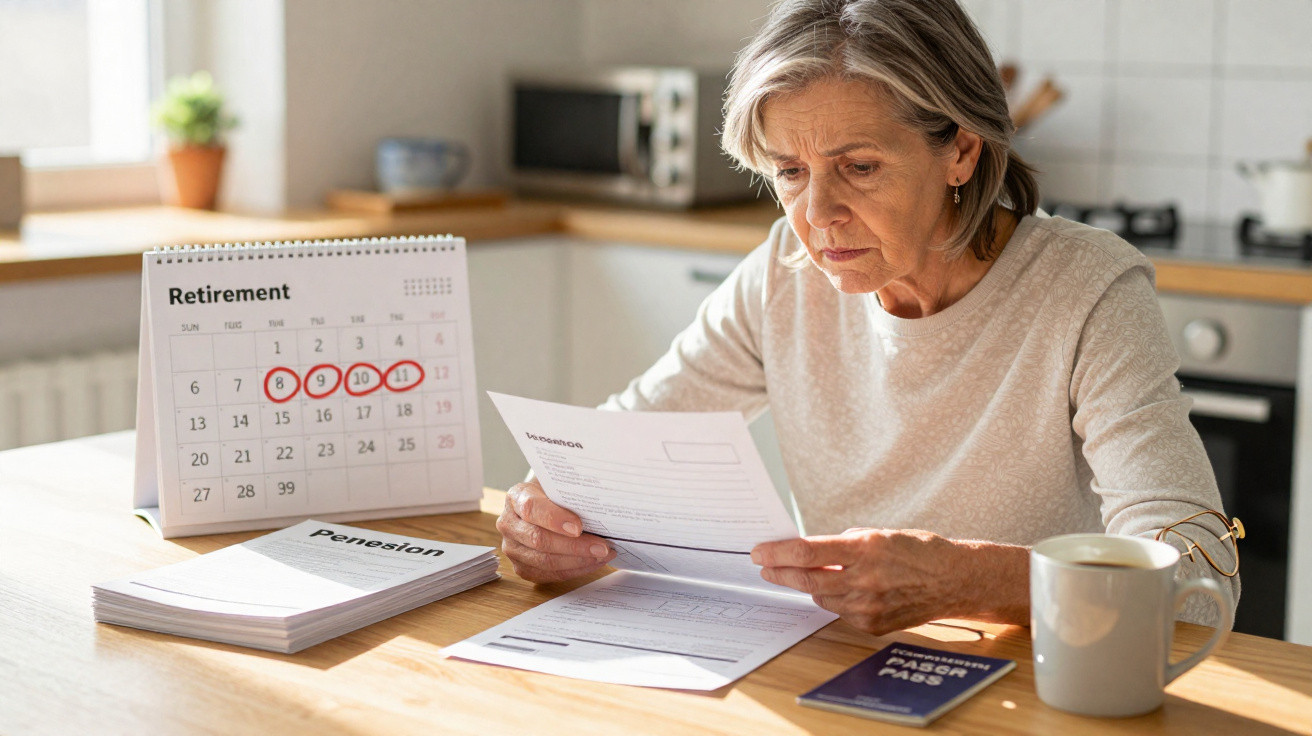
The Monday after their leaving do, Sylvie put her alarm clock away in a drawer. Alain kept his on the bedside table, “just in case”, he joked. After more than forty years at work, the couple had already pictured their first free month: a few meals with the grandchildren, a weekend on the coast and that long-planned kitchen refurbishment. Their expected pension income seemed comfortable, even reassuring. Then, one week after leaving their offices, a letter and a bank statement changed the mood. The money they expected was not there. Or, rather, not yet. Between their final salary, payment dates and the various pension schemes, their timetable looked nothing like the one they had imagined. Freedom suddenly had an odd aftertaste.
The first month of retirement can bring a very practical surprise
For Sylvie and Alain, there was nothing unusual about the trap: like many employees, they had made an assumption. Until their final day at work, a salary arrives every month on an almost fixed date, and it is easy to think that this pattern will never change. Retirement does not always follow the same logic, however. Depending on the pension provider, payments may be made in arrears, creating a gap that turns the first few weeks into uncertain territory. On paper, their income remained comfortable. In real life, they still had to cover rent, direct debits, food shopping and car insurance before the first transfer arrived. We all know that moment when an expected sum feels guaranteed-until it is genuinely missing from the account.
Alain left his company on 31 August, convinced that his September pension would arrive during the first days of the month. He had even booked a four-night break in Brittany, with no extravagance involved: €680, payable on arrival. When he checked his retirement account online, he realised that the state pension is generally paid at the beginning of the following month for the month just ended. September's income may therefore not appear until October, depending on the pension fund's timetable and the bank. Sylvie, who also receives a supplementary pension, found that its payment date could be different. Their annual budget worked perfectly well. Their budget for the first thirty days, however, contained an unexpected gap.
This does not mean the pension has vanished or that the application is necessarily causing difficulties. It mainly highlights an administrative detail that people often consider too late: the transition from salary to retirement can create a period without regular income arriving. The final pay packet may include accrued holiday pay, compensation or a final settlement, but it can also be reduced if the leaving date was not planned carefully. State, supplementary and any additional pension schemes do not all operate to the same timetable. Retirement often begins in the mind before it begins on the bank statement. Even a short delay can be enough to disrupt plans made over many years.
What they wish they had checked before handing in their passes
The first useful step is to draw up a very straightforward, almost school-style calendar covering two or three months. On one side, record the precise contract end date, the estimated payment date for the final salary, any holiday pay and direct debits that have already been scheduled. On the other, list the expected pension payment dates for each scheme. Sylvie eventually did this on a sheet of squared paper, placed between the coffee machine and the fruit bowl. The result surprised her: their first full payment did not line up with their usual outgoings. A modest cash buffer-even one equal to a month's bills-can prevent people from dipping into savings set aside for holidays or emergencies.
A common mistake is to look only at the total shown on the pension forecast. That figure is reassuring and makes everything seem settled, but it does not answer the most down-to-earth question: “What day does the money actually arrive?” Let us be honest: nobody really does this every day. We are more likely to check the price of a train ticket than the exact schedule of our future bank transfers. Yet a few calls or checks of personal online accounts will often remove any uncertainty. It is also important to confirm that every application was submitted on time, that bank details are correct and that no supporting document is holding up the award of an entitlement.
Alain would have liked someone to tell him one very simple thing during his exit meeting: do not schedule your first retirement expenses before you have seen the first transfers arrive. This caution does not stop anyone enjoying the change; it simply prevents excitement from turning into unnecessary stress.
“A comfortable retirement does not protect you from a difficult month if payment dates have not been checked carefully.”
- Check the payment date for every pension scheme.
- Keep a buffer for fixed costs during the first few weeks.
- Postpone major spending until the first payments can be seen in the account.
- Contact the pension provider promptly if the application still shows as incomplete or pending.
A comfortable pension does not remove the need to check the small details
A week after discovering the problem, Sylvie and Alain cancelled their weekend in Brittany. There was no drama, though they felt a touch of disappointment. Instead, they had lunch with friends and went for a walk beside a lake an hour from home. Their pension was not in doubt, nor was their kitchen project. They simply delayed the spending by a few weeks. This story will resonate with many future retirees because it highlights an unglamorous truth: financial peace of mind also depends on the timing of money coming in. The amount matters, of course. The date matters just as much when bills continue to arrive without waiting.
| Key point | Detail | Benefit for the reader |
|---|---|---|
| Payment delay | Some pensions are paid after the month to which they relate. | Avoid confusing the retirement date with the date the money is received. |
| Final salary | It varies according to the contract end date, holiday entitlement and final settlement. | Plan for income that is genuinely available in the short term. |
| Cash buffer | A margin covering fixed expenses protects the first month. | Enjoy retirement without unnecessary bank-related stress. |
FAQ:
- Why does my first retirement pension not arrive straight away? Because some pension providers pay in arrears: payment is made after the month it covers.
- Is the supplementary pension paid on the same day as the state pension? Not necessarily. Each scheme has its own timetable, which should be checked before leaving work.
- Should I keep savings available before retiring? Yes, a reserve covering at least the first month's regular expenses provides real security.
- What should I do if payment is delayed beyond the stated date? Check your online application, your bank details, then contact the relevant pension provider.
- Can I arrange a trip at the very start of retirement? Yes, provided you fund it with cash already available rather than a pension that has not yet been paid.
Comments
No comments yet. Be the first to comment!
Leave a Comment