
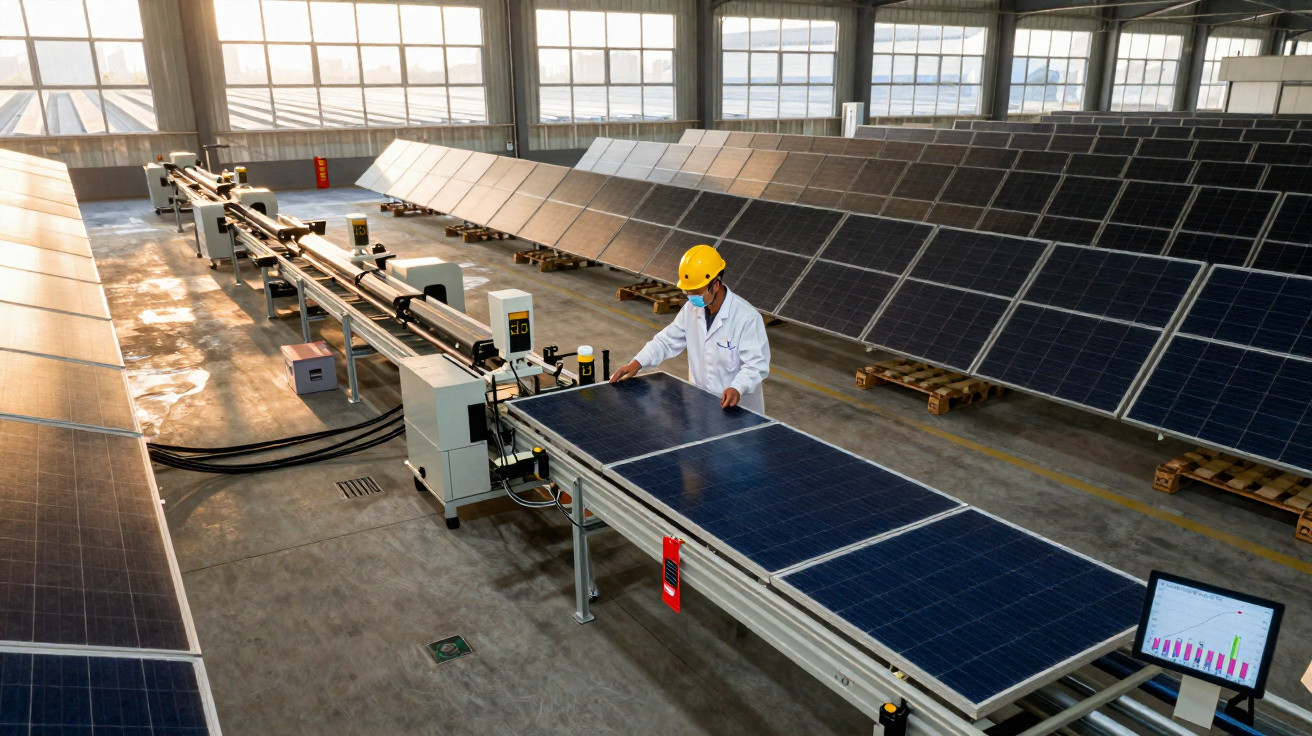
Today, those very same panels are accumulating in warehouses, their prices are tumbling, and Beijing is discreetly telling factories to cut output or stop production lines altogether. The nation that inundated global markets with solar equipment is applying the brakes before the entire sector breaks down. What happens next could alter the course of clean energy from Shanghai to Sacramento.
On a smoggy morning in Jiangsu province, the solar boom looks nothing like a miracle. It resembles a stream of weary workers leaving a factory where the lights remain on but the orders have vanished. In the yard outside, lorries stand unused, carrying panels nobody is rushing to pick up. The manager checks his phone as spot prices fall further each week, watching his margins disappear pixel by pixel. This is the bleak underside of a success story that expanded too far, too quickly. Between climate ambition and hard-nosed industrial strategy, something has given way.
The boom that became a solar glut
Visit any large Chinese solar manufacturing centre and the problem is obvious: there are simply too many panels. For ten years, Beijing channelled subsidies, low-cost loans and political backing into creating the world’s biggest solar manufacturing system. It succeeded almost too effectively. Huge factories opened one after another, each claiming to be more efficient, automated and unstoppable than its predecessor. They were all pursuing the same objective: to control global solar in the way China came to dominate steel and smartphones.
The figures make the point more clearly than any political slogan. By 2024, Chinese firms could manufacture vastly more solar modules than the world could fit in a single year. Over roughly eighteen months, module prices dropped by more than half, reaching levels that would have looked unbelievable only a few years earlier. That is excellent news for panel buyers, but punishing for manufacturers. Exports climbed sharply, yet unsold stock rose as well, particularly in Europe, where ports and warehouses quietly became vast solar-panel storage sites. It is like a party where the music continues while half the guests are already searching for the way out.
Economists describe this as overcapacity; for workers on the factory floor, it feels more like an approaching precipice. When every competitor expands simultaneously, none wants to be the first to stop. In China, local authorities frequently supported additional factories because growth statistics mattered, even when the market was already full. Beijing is now confronting the price of its own achievement: a globally dominant sector that is also perilously fragile. The government is therefore considering tighter standards, limits on new schemes and discreet pressure for smaller or less advanced factories to close. The goal remains the same, but the pace is changing.
How China is seeking to prevent a solar crash
The approach appears straightforward: remove the weakest plants and make the survivors mature. Official policy papers refer to “orderly” development and “high-quality” capacity. In reality, that involves fresh licensing requirements, stricter efficiency benchmarks and credit that no longer reaches every hopeful start-up with a wafer line and a pitch deck. If your technology is outdated, your energy consumption is excessive or your costs are inflated, you are at risk of being cut. The warning is unmistakable: become world-class or cease to exist.
For overseas purchasers, this is where the picture becomes complicated. The exceptionally low prices of Chinese panels were not an accident; they emerged from this industrial arms race. Many developers across Europe, Africa and Latin America designed entire solar programmes on the expectation that modules would remain remarkably cheap. They are now seeing Chinese manufacturers consolidate, trade friction intensify and import restrictions become tougher. Some worry that, once weaker factories have disappeared, prices could start rising again or supply could become more politicised. It is also difficult not to sympathise with workers who helped power a worldwide green surge and now risk being abandoned by it.
From Beijing’s viewpoint, retrenchment is about survival rather than generosity. An unchecked price war can destroy even the strongest competitor. A solar panel is not just a product; it’s a piece of industrial strategy bolted onto a roof. China still intends to set the speed and direction of the global transition, from polysilicon through to advanced back-contact cells. Closing or merging factories offers a means of retaining that control while avoiding a dramatic collapse that would give influence to rival producers in the US, India or Europe. It is a hazardous bet, but allowing the market to tear itself apart would be worse.
What China’s solar glut means for the rest of the world
For policymakers and energy purchasers beyond China, this turmoil offers a quiet lesson: do not base your clean-energy future on one highly concentrated supply chain. A practical first move is to trace where panels genuinely originate - not merely the brand name, but the sites where wafers and cells are produced. Once that is understood, governments and major buyers can steadily spread their contracts: combining Chinese supply with regional manufacturing, long-term procurement agreements and smaller specialist providers. It is much like avoiding putting an entire retirement fund into a single share, however unbeatable that share may appear.
The change in outlook is different for households and small businesses. Many postpone solar installation because they expect prices to fall further still. China’s shake-up suggests that reasoning could date quickly. Delaying for another year to save a few pence per watt may prove costly if trade rules tighten or subsidies alter. Let’s be honest: nobody really spends hours every day monitoring panel prices like a trader. Eventually, securing a sensible deal with a reliable installer is better than pursuing the absolute lowest offer. That is especially true when the real aim is a reduced electricity bill and a degree of independence, rather than winning a competition over price timing.
Global competitors are attempting to interpret this moment too. In Brussels, Washington and New Delhi, policymakers see China’s excess capacity as both a danger and an opportunity. Some are increasing tariffs or subsidy programmes to shield domestic factories, while others continue quietly buying low-cost Chinese modules because they help meet national climate targets faster. One European developer put it bluntly:
“Without China’s flood of panels, half our solar projects would still be PowerPoints.”
That conflict will not disappear. It will influence both the pace and the fairness of the energy transition.
- China’s solar surplus holds down prices, but it also makes global supply less stable.
- Chinese factory closures could lift prices or make deliveries less predictable.
- Incentives for domestic manufacturing elsewhere can lower risk, but need years to reach scale.
The fragile future of a ‘cheap solar’ world
There is a striking irony at the centre of this story. The overcapacity troubling Chinese producers has also been a lifeline for climate policy. Extremely cheap panels made solar the standard choice in numerous markets, including those with difficult politics or deeply established fossil fuels. If Beijing succeeds in bringing order to the disruption - reducing factory numbers and steering prices towards a more sustainable level - the world may need to confront what clean energy truly costs when a single industrial giant is not cross-subsidising it. That would not end the transition, but it would make it more mature and perhaps less idealistic.
At a personal level, the solar surplus reflects something about us as well. We are drawn to the prospect of green technology becoming endlessly cheaper, faster and lighter, with no compromises. Then reality arrives in the form of warehouse staff, trade disputes, brownfield factory locations and communities asking what follows once the boom is over. We have all experienced the moment when a promise that seems too good eventually reveals its limits. The panels on a neighbour’s roof reveal nothing about the night shift in Anhui or the Shenzhen bank meeting where a loan is quietly withdrawn. Yet those realities are all included in the price on the quotation you receive.
Perhaps that is the necessary, uncomfortable idea to consider. The era of “China will make it cheap, forever” is becoming unsteady. It is not ending, but it is wavering. Countries that depended on that assumption will need to reassess their plans. Investors must account for policy risk as well as hours of sunshine. Homeowners will consider not just the cost per watt, but where and how their panels were manufactured. Solar’s future remains bright, although the route towards it is less seamless than marketing implies.
| Key point | Detail | Why it matters to the reader |
|---|---|---|
| China’s solar overcapacity | Factories can make far more panels than the world installs each year | It explains why prices have collapsed - and why that situation may not continue |
| Planned factory closures | Beijing is encouraging weaker or outdated plants to close or merge | It indicates a turning point that could affect worldwide panel prices and availability |
| Need to diversify supply | Governments and buyers are considering non-Chinese sources and domestic manufacturing | It presents ways to reduce reliance on one country for vital green technology |
FAQ:
- Why did China build so much solar capacity in the first place? Beijing regarded solar as a strategic industry: a route to reduce pollution, secure global technological leadership and create employment. Generous subsidies, inexpensive land and accessible credit encouraged companies to expand aggressively, even where demand did not fully support it.
- Does the glut of Chinese panels mean solar will stay cheap forever? Not necessarily. Prices are exceptionally low now because competition is intense and supply exceeds demand. If weaker factories close and trade rules become tighter, costs could level off or increase slightly, particularly in markets that impose tariffs.
- Should homeowners rush to install solar before prices change? For many people, waiting for panels to become marginally cheaper is less beneficial than securing lower energy bills sooner. If you have a sound quotation from a reputable installer and stable incentives, acting is often more sensible than waiting for perfect timing.
- How are other countries responding to China’s dominance? Areas including the US, EU and India are providing subsidies, tax credits and trade protection to establish their own solar factories. These initiatives need time, however, so Chinese panels remain dominant in the short term.
- Is this crisis bad for global climate goals? It works in both directions. The current surplus has made clean electricity cheaper and quicker to deploy. If China restricts capacity too sharply, or trade tensions intensify, some projects could be delayed. Over the longer term, a more balanced and resilient supply chain could make the transition more robust.
Comments
No comments yet. Be the first to comment!
Leave a Comment